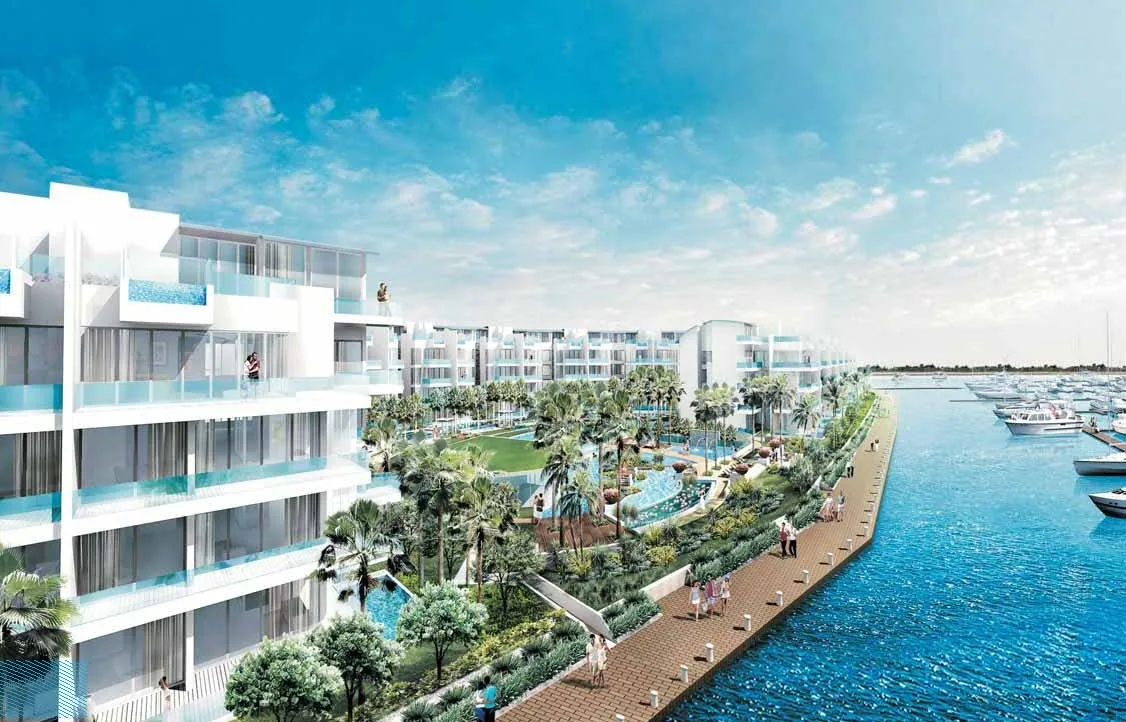
 Artist’s impression
This TDSR calculator for Marina Collection works out the largest home loan an income can carry under the MAS Total Debt Servicing Ratio, then sets it against the loan-to-value limit on the price to show which rule decides the loan. Illustrative figure, enter your own price: the price field opens at $1,500,000, a round number that is not the price of any home at the development; the Sales Concierge sends the current price list on request. The rules behind it are explained on the housing loan information page.
Main Applicant
Counted after a 30% haircut.
Car, personal and other property loans.
Joint Applicant
Counted after a 30% haircut.
Car, personal and other property loans.
Illustrative figure, enter your own price.
Up to 35 years for private property.
Anything below 4% is tested at 4%.
Sets the loan-to-value limit.
Indicative only. A tenure over 30 years, or a loan running past age 65 (income-weighted for joint applicants), moves the loan to the lower LTV limit of 55%, 25% or 15% depending on loans outstanding, and lifts the minimum cash on a first housing loan from 5% to 10%. Where the LTV limit is lower than the TDSR figure, the LTV limit decides the loan. Banks apply their own credit policies; confirm with a bank, or ask the Sales Concierge to arrange an in-principle approval. Leave out any existing home loan that will be repaid before this purchase.
How a Loan Is Sized at Marina Collection
The bank begins with assessed income: fixed salary in full, plus variable income such as bonuses at 70% after the haircut, averaged over twelve months. Up to 55% of it may go to debt each month, so existing repayments come off first and what remains is turned into a loan at the MAS medium-term rate, the higher of a 4% floor or the loan’s thereafter rate, over the tenure chosen.
Joint buyers are assessed on their income-weighted average age. A tenure beyond 30 years, or a loan that runs past age 65 on that average, moves the loan to the lower LTV limit with a larger cash share, and the smaller of the TDSR and LTV figures becomes the loan.
The Completed-Sale Timetable at Marina Collection
Marina Collection received its Temporary Occupation Permit on 11 March 2011, so a purchase follows the timetable of a completed home: the price is paid in three sums over about ten weeks, and the whole loan is drawn on the day of legal completion. The sale terms in the current fact sheet are a 1% option fee, 4% on exercise within two weeks and the 95% balance on completion in eight weeks.
- Option to purchase: 1% option fee. Paid on the grant of the option; it reserves the home while the buyer arranges the loan.
- Exercise of the option: 4%, within 2 weeks. Paid when the buyer signs and exercises the option; together with the option fee it makes 5% of the price.
- Stamp duty: Within 14 days of signing. Buyer’s Stamp Duty and any ABSD are paid to IRAS within 14 days of the exercised option.
- Legal completion: 95%, in 8 weeks. The balance is paid from the bank loan, CPF and cash, and the keys are handed over: the home is ready to occupy.
The two early sums together make 5% of the price, which is the minimum cash downpayment MAS requires on a first housing loan at the 75% limit. On that loan, the 95% paid at completion is met by the bank’s 75% and a further 20% from cash or CPF savings; with a second or third housing loan, or at the lower limit, the cash share and the downpayment are larger, as the housing loan page shows. Stamp duty is paid to IRAS within 14 days of signing, which for a completed home means within 14 days of exercising the option.
Sources: the sale terms in the current fact sheet (23 October 2026); IRAS (stamping deadline: within 14 days after signing); MAS (LTV limits and minimum cash); CPF Board (use of CPF savings), checked 25 October 2026. The option to purchase and the sale documents for a particular home govern.
Stack this result with the duty on the stamp duty calculator, or ask the Sales Concierge to go through the figures for a particular home on the current price list.
Request the Marina Collection Price List
Marina Collection is completed and open for sale. The Sales Concierge sends the current price list and the homes still open for selection. Showflat viewings are arranged by appointment through the Sales Concierge.
Sent on request
- The current price list and the homes still open for selection.
- The e-brochure and the floor plans you shortlist.
- The stamp duty for your profile and a loan estimate from the TDSR calculator.
- A showflat appointment at a time that suits you.
Request the Price List
No obligation. The Sales Concierge responds personally to every enquiry.
Prefer to speak to someone? Call +65 6200 6220, or send a WhatsApp message to the same number.